The Greenhouse Gas (GHG) Protocol is the global standard for measuring and reporting corporate emissions. In Australia, it underpins mandatory climate reporting under the Australian Sustainability Reporting Standards (ASRS). AASB S2 is the mandatory climate standard within the ASRS, and it requires companies to measure emissions using the GHG Protocol. If your organisation is preparing an ASRS sustainability report, your emissions numbers will be built on it.
This guide covers what the GHG Protocol is, how it connects to AASB S2 and NGER, and the changes coming over the next few years.
About the GHG Protocol
The World Resources Institute (WRI) and the World Business Council for Sustainable Development (WBCSD) set up the GHG Protocol in 1998. Its Corporate Standard, published in 2004, gives companies a consistent method for building an emissions inventory.
It is the most widely used carbon accounting framework in the world. Most large listed companies use it, as do CDP, the Science Based Targets initiative (SBTi) and the ISSB standards that AASB S2 is based on.
For finance teams, the GHG Protocol does a similar job to accounting standards. It defines the reporting boundary, what gets counted, and how to present the results so they can be compared and assured.
The three scopes
The GHG Protocol groups emissions into three scopes.
Scope 1 covers direct emissions from sources you own or control. Examples include fuel burnt in company vehicles, gas used in boilers and refrigerant leaks.
Scope 2 covers indirect emissions from the electricity, heat or steam you buy. Companies report Scope 2 two ways. The location-based method uses average grid emission factors. The market-based method reflects your energy contracts and certificates, such as Large-scale Generation Certificates (LGCs).
Scope 3 covers all other indirect emissions across your value chain. The Scope 3 Standard splits these into 15 categories, from purchased goods and services through to the end-of-life treatment of sold products. For most companies, Scope 3 makes up the bulk of the footprint.
Key standards in the GHG Protocol suite
The GHG Protocol publishes several standards. Three matter most for corporate reporting:
- Corporate Standard: The base method for Scope 1 and 2 inventories, including how to set organisational boundaries.
- Scope 2 Guidance: Detailed rules for location-based and market-based electricity accounting.
- Scope 3 Standard: The method for measuring value chain emissions across the 15 categories.
The suite also includes a Product Standard for lifecycle emissions, a Project Protocol for mitigation projects, and standards for cities, national goals and policy assessment. These are useful context. Most Australian companies reporting under AASB S2 will work mainly with the three corporate standards above.
How the GHG Protocol connects to AASB S2
AASB S2 requires entities to measure Scope 1, 2 and 3 emissions in line with the GHG Protocol Corporate Standard (2004). Jurisdictional relief lets Australian entities use NGER methods where they apply.
Many Group 1 companies already report under the National Greenhouse and Energy Reporting (NGER) scheme. NGER data is a strong starting point, but it doesn't cover everything AASB S2 needs. The main gaps are:
- Scope 3: NGER doesn't cover Scope 3. AASB S2 does.
- Boundary: NGER uses operational control only. AASB S2 lets you choose operational control, financial control or equity share, and the choice should match your financial reporting.
- Reporting period: NGER runs on the 1 July to 30 June year. AASB S2 follows your financial year.
- Coverage: NGER has facility thresholds. AASB S2 needs the whole reporting entity, including smaller sites and overseas operations.
Finance teams should treat NGER as one input and run a reconciliation to close these gaps.
AASB S2 also includes transition relief. Entities don't need to disclose Scope 3 in their first reporting period. Scope 3 statements also get modified liability protection for reporting periods starting between 1 January 2025 and 30 June 2028. Group 2 entities began their first reporting period on 1 July 2026, and Group 3 follows from 1 July 2027.
Why Scope 3 needs early attention
Scope 3 is the hardest part of the inventory to get right. The data sits with suppliers, customers and partners, so it's harder to collect and verify.
Most companies start with spend-based estimates, which apply emission factors to financial spend. This gets you a complete first view quickly. Over time, you can move high-impact categories to activity-based or supplier-specific data for better accuracy.
The modified liability window is a practical chance to build this capability. By the time it closes, auditors will expect a documented method, clear assumptions and a data trail back to source. Assurance requirements also scale up over time, reaching reasonable assurance across all scopes for reporting periods starting from 1 July 2030.
What's changing in the GHG Protocol
The GHG Protocol is going through its biggest update since 2004. On 29 July 2026, it confirmed a partnership with ISO to combine its corporate standards with ISO 14064-1 into one co-branded standard.
The new consolidated Corporate Standard (Version 3.0) will bring the Corporate Standard, Scope 2 Guidance and Scope 3 Standard into one document. It will have two parts. Part 1 covers general requirements and the physical GHG inventory. Part 2 covers actions and market instruments, such as renewable energy certificates and offsets.
The key dates:
- Q2 2027: Public consultation on the draft consolidated standard.
- Q4 2028 (estimated): Publication of the revised standard.
Scope 2 is a major focus. The consultation, which closed in January 2026, looked at tighter market-based rules, including time-matching and requiring certificates to come from the same grid as the electricity used. If adopted, these changes could affect how Australian companies use LGCs and Guarantee of Origin certificates to report lower Scope 2 emissions.
AASB S2 currently refers to the 2004 Corporate Standard. Any move to the new version would need a change to the Australian standard. Finance teams should track the process now, especially if renewable electricity procurement is a large part of their decarbonisation plan.
Getting your inventory audit-ready
Strong GHG Protocol reporting relies on the same controls as financial reporting. Priorities for CFOs:
- Set your boundary: Choose a consolidation approach that lines up with your financial statements and document the reasons.
- Document methods: Record emission factors, data sources, assumptions and estimates for every category.
- Build controls: Apply review, approval and version control to emissions data, as you would for financial data.
- Screen Scope 3: Identify your most material categories and prioritise data improvements there.
- Plan for change: Keep an eye on the Scope 2 and consolidated standard updates and model how they could affect reported emissions.
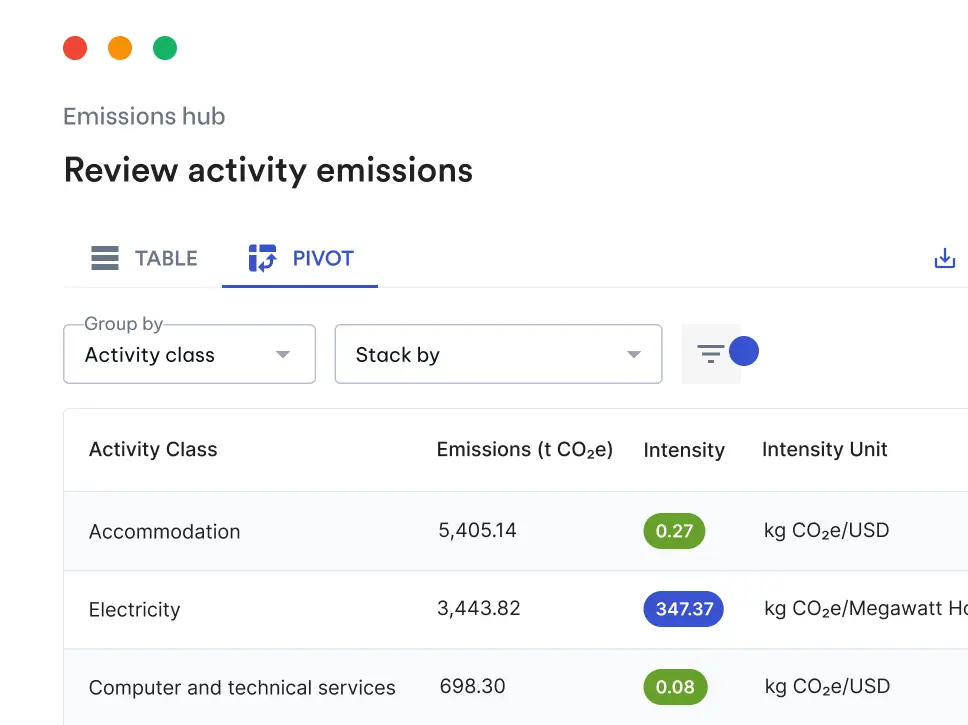
Carbon accounting software can take much of the manual work out of this process. Avarni uses AI to map financial and activity data to emission factors across all three scopes, with an audit trail that supports AASB S2 assurance.
Summary
- About the GHG Protocol: The GHG Protocol is the global framework for corporate emissions reporting. It was set up by WRI and WBCSD in 1998.
- The three scopes: Emissions fall into Scope 1 (direct), Scope 2 (purchased energy) and Scope 3 (value chain). Scope 3 is usually the largest share.
- Key standards: The Corporate Standard, Scope 2 Guidance and Scope 3 Standard are the core documents for corporate reporting.
- Connection to AASB S2: AASB S2 requires GHG Protocol measurement, and NGER methods can be used where they apply. Companies need to close gaps in Scope 3, boundary, period and coverage.
- Scope 3 priority: Transition relief and modified liability give companies time to build solid Scope 3 methods before assurance requirements tighten.
- What's changing: The GHG Protocol and ISO are merging their corporate standards. Consultation is expected in Q2 2027 and publication in Q4 2028, with Scope 2 rules a key focus.
- Audit readiness: Treat emissions data like financial data, with a clear boundary, documented methods and strong controls.
This article was originally published on 14 February 2023.