
The business case for carbon accounting software in 2026 rests on four numbers a CFO already tracks: compliance risk, Scope 3 effort, assurance cost and reporting hours. With mandatory climate reporting now in force for Group 1 and Group 2 entities, emissions data sits in the annual report, signed off by directors and reviewed by auditors. That moves the software decision from the sustainability team's wish list to the finance team's budget.
This guide shows Australian finance and sustainability leaders how to build a carbon accounting cost justification that stands up in front of a CFO, an audit committee and a board. It covers what has changed in Australian sustainability reporting, the four value pillars, a worked ROI framework and a checklist for evaluating sustainability reporting software.
What's changed in Australian sustainability reporting
Australian sustainability reporting is now law under the Corporations Act, with climate disclosures prepared to AASB S2 and assured under ASSA 5010. Entities are phased in by size, and Group 2 periods starting on or after 1 July 2026 are already underway.
Source: ASIC Regulatory Guide 280 Sustainability reporting, Table 2
Three shifts matter most for the budget conversation:
- Scope 3 is coming into scope. AASB S2 gives relief from Scope 3 disclosure in the first reporting year only (AASB). Scope 3 must be disclosed, and assured, from year two.
- Assurance tightens over time. Limited assurance now moves to reasonable assurance of all mandatory climate disclosures for years starting on or after 1 July 2030 (AUASB).
- Liability protection is temporary. Modified liability for Scope 3, scenario analysis and transition plans covers reports for years starting 1 January 2025 to 31 December 2027 (ASIC RG 280).
Treasury's 2026 consultation, Improving the efficiency of climate-related financial disclosures, looked at changing assurance rules to reduce compliance costs, clarifying key terms and reducing the burden of supply-chain information requests. Treasury has said it will sequence any changes to avoid disruption. Whatever the outcome, the direction is the same: more scrutiny of emissions data, not less.
Pillar 1: Compliance risk is now a balance-sheet issue
The first line of any carbon accounting cost justification is risk avoided. The sustainability report is part of the annual report, so directors make a declaration on it and the Corporations Act's misleading-disclosure and civil penalty regimes apply.
Spreadsheet-based emissions inventories create exactly the risks regulators look for:
- Completeness issues. Your financial and operational data have to reconcile seamlessly with each other to pass audit, with any gaps estimated. It’s impossible to identify gaps in operation data in the first place without this step.
- Broken formulas and version drift. One overwritten cell can change a reported total, with no record of who changed it or why.
- Out-of-date emission factors. NGA Factors and other datasets are updated regularly. Manual workbooks often lag.
- Inconsistent boundaries. Operational and financial control boundaries must match the financial statements. Without a system enforcing this, entities and facilities slip in or out.
- Greenwashing exposure. Climate claims in marketing, investor decks and tenders must reconcile with the audited numbers.
Modified liability gives some breathing room for Scope 3 and scenario analysis for reporting periods starting up to 31 December 2027, but it does not cover governance failures, late lodgement or Scope 1 and 2 errors. When finance leaders frame this pillar, the question is simple: what would a material misstatement, a qualified assurance conclusion or a regulator inquiry cost us in fees, remediation and reputation?
Pillar 2: Scope 3 emissions calculation is where the hours go
Scope 3 is usually the largest share of a company's footprint and the hardest to calculate. It spans up to 15 GHG Protocol categories, from purchased goods and services to business travel, freight and the use of sold products. Most of the data sits outside the sustainability team: in accounts payable, procurement, fleet and supplier systems.
A manual Scope 3 emissions calculation typically means:
- Exporting the general ledger and mapping thousands of spend lines to emission categories.
- Matching each category to the right emission factor, often by hand.
- Chasing suppliers for primary data in emails and spreadsheets.
- Estimating energy and fuel consumption of sold products, as well as estimating the emissions impact when they are disposed.
- Repeating the whole exercise every year, or every quarter for internal targets.
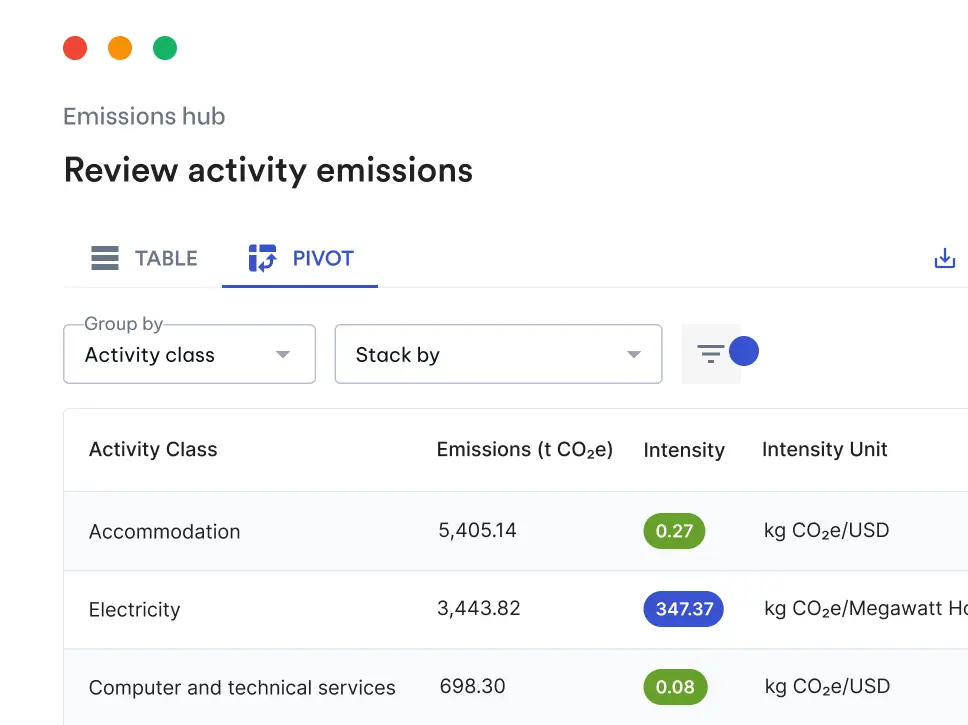
Carbon accounting software automates the repeatable parts. Ledger data flows in directly, spend is classified against maintained factor libraries, and supplier-specific data replaces spend-based estimates as it becomes available. The result is a Scope 3 inventory that improves year on year instead of being rebuilt from scratch.
This matters for the budget, too. Treasury's consultation flagged reliable domestic emission factors and clearer supplier-request boundaries as priorities, which signals that factor quality and value-chain data management will be scrutinised. Software that keeps factors current and records data sources gives finance teams a defensible method.
Pillar 3: Audit readiness lowers assurance cost
Assurers charge for time, and messy data takes time. Under ASSA 5010, your auditor needs to trace each reported number back to source data, the emission factor applied and the person who approved it. The move toward reasonable assurance raises that bar further, because reasonable assurance demands evidence similar to a financial statement audit.
Audit-ready emissions data has four features:
- Traceability. Every figure links to its source transaction, invoice or meter reading.
- Version control. Changes are logged with a timestamp, user and reason.
- Documented methodology. Boundaries, factor sources and estimation methods are recorded once and applied consistently.
- Controls and approvals. Review and sign-off steps mirror the financial close.
Spreadsheets can do some of this, but only with heavy manual effort that the assurer then has to test. Enterprise sustainability management platforms build these controls in. For finance leaders, the benefit shows up as fewer audit queries, shorter fieldwork, lower fees and less risk of a modified assurance conclusion.
The Treasury consultation's option to keep reasonable assurance for Scope 1 and 2 only does not remove the need. Limited assurance still requires evidence, and Scope 1 and 2 would face the highest bar.
Pillar 4: Reporting time savings free up senior staff
The most visible saving is people's time, especially in the weeks before year-end. Climate disclosures now run on the financial reporting calendar, so emissions work competes with the close for the same finance and sustainability staff.
To quantify this pillar, ask each contributor how many hours they spent on last year's inventory, then multiply by a fully loaded hourly rate. Include external consultant fees for calculations or data clean-up. Most organisations underestimate this number until they add it up.
How to build your carbon accounting cost justification
A strong business case counts the hard savings, then treats risk reduction as upside. CFOs trust conservative numbers, so keep compliance risk out of the core ROI and present it separately.
Step 1: Establish your baseline
Add up what your current approach really costs each year: internal hours across sustainability, finance, procurement and operations; consultant fees; and the share of assurance fees driven by emissions data.
Step 2: Estimate the savings
Apply realistic reductions to each line. Use vendor case studies and reference calls to test your assumptions.
Step 3: Calculate ROI and payback
ROI = (Annual savings − Annual software cost) ÷ Annual software cost
Step 4: Add the risk and strategic case
List the risks reduced (misstatement, qualified assurance, greenwashing claims) and the strategic gains (supplier engagement, decarbonisation planning, tender requirements) without forcing a dollar value on them.
Worked example
The figures below are illustrative only. They describe a hypothetical Group 2 manufacturer and are not a price quote.
On these assumptions, the software pays for itself if its total annual cost, including subscription, implementation and training, is under $229,000. That's before counting any compliance risk avoided. Swap in your own numbers, then use the ROI formula above with the quotes you receive.
What to look for in sustainability reporting software
The right platform is the one that holds up under Australian assurance, not the one with the most features. Use this checklist when shortlisting vendors:
- Built for Australian sustainability reporting: outputs aligned to AASB S2, NGA Factors and NGER methods, plus local support.
- Scope 3 depth: coverage of all relevant GHG Protocol categories, with a path from spend-based to supplier-specific data.
- Scientific credibility: transparent, peer-reviewed or research-backed calculation methods and factor sources.
- Audit trail: source-level traceability, change logs and approval workflows your assurer can test.
- Finance-system integration: direct connections to your ERP and accounting platforms to cut manual exports.
- Scalability: handles multiple entities, facilities and reporting boundaries as your group grows.
- Decarbonisation tools: reduction targets, scenario modelling and transition planning in the same platform.
- Total cost of ownership: subscription, implementation, training and the internal time needed to run it.
Ask each vendor for an Australian reference customer that has been through assurance using their platform. It is the fastest way to test claims.
Frequently asked questions
What is carbon accounting software?
Carbon accounting software measures, manages and reports an organisation's greenhouse gas emissions across Scope 1, 2 and 3. It replaces spreadsheets with automated data collection, maintained emission factors and an audit trail that supports assurance.
How do you justify the cost of carbon accounting software?
Compare the annual cost of the software with the internal hours, consultant fees and assurance effort it replaces. Then present compliance risk reduction and strategic benefits as additional upside rather than part of the core ROI.
Is carbon accounting software required for Australian sustainability reporting?
No law requires software. However, Group 1, 2 and 3 entities must report emissions under AASB S2 and obtain assurance, which is difficult to do reliably and efficiently with spreadsheets.
When do Australian companies need to report Scope 3 emissions?
Scope 3 emissions are required from an entity's second reporting year under AASB S2. For Group 2 entities with periods starting 1 July 2026, that means the year starting 1 July 2027.
What's the difference between sustainability reporting software and enterprise sustainability management platforms?
Sustainability reporting software focuses on producing disclosures. Enterprise sustainability management platforms also cover data governance, supplier engagement, target setting and decarbonisation planning across the business.
How long does implementation take?
It depends on data readiness and the number of entities. Start at least one full reporting period before your first mandatory year so you can test the data and the audit trail.
Make the case before year-end
Carbon accounting software pays for itself when you count the hours, fees and risk your current process already carries. Group 2 entities are reporting now, Scope 3 follows in year two, and assurance is only getting stricter. Every reporting cycle run on spreadsheets adds cost you will pay again next year.
Avarni is a CSIRO-backed carbon accounting platform built for Australian sustainability reporting. It helps finance and sustainability teams calculate Scope 1, 2 and 3 emissions, prepare AASB S2 disclosures and stay ready for assurance.
Book a demo to see how Avarni can support your business case.